Table of contents
- Your Options at a Glance: In-House CSR vs. Generalist VA vs. Insurance-Trained VA
- Why South Carolina Insurance Agencies Are Turning to Virtual Assistants
- What South Carolina Law Lets Virtual Assistants Do for Insurance Agencies
- Data Security for Virtual Assistants at South Carolina Insurance Agencies
- What to Look for in Virtual Assistants for Insurance Agencies in South Carolina
- How XAssure’s Virtual Assistants Support South Carolina Insurance Agencies
- What Do Virtual Assistants for Insurance Agencies in South Carolina Cost?
- How to Onboard Virtual Assistants in South Carolina Insurance Agencies
- Summing Up
- Frequently Asked Questions
- Also Reads
South Carolina insurance agencies work in a market shaped by weather. Hurricanes and tropical storms threaten the coast from the Grand Strand to Hilton Head, severe storms and flooding reach the Upstate, and coastal property often needs wind pool placements alongside standard policies. Add a tight hiring market for experienced CSRs, and it’s easy to see why more owners are looking at virtual assistants for insurance agencies in South Carolina.
This guide compares your staffing options, explains what South Carolina’s licensing law allows an unlicensed VA to do, covers the state’s insurance data security law, sets out realistic costs, and shows how to onboard a VA in your agency.
Your Options at a Glance: In-House CSR vs. Generalist VA vs. Insurance-Trained VA
Most South Carolina agency owners are choosing between three ways to add service capacity. Here is how they compare.
| In-house CSR | Generalist offshore VA | Insurance-trained VA (XAssure) | |
|---|---|---|---|
| Estimated annual cost | $53,000–$72,000 | Roughly $8,000–$17,000 | $12,600 (part-time) to $24,000 (full-time) |
| Time to start | Often months to recruit | Days, then weeks of training | Onboarded in 7–10 days |
| Knows your AMS and carrier portals | Depends on the hire | No, you train them | Yes: AMS 360, Applied Epic, EzLynx, HawkSoft, NowCerts, QQ Catalyst |
| Understands licensed vs. unlicensed limits | Needs training | Rarely | Yes, built into every SOP |
| Data security controls | Your office, your policies | Varies widely | MFA, encrypted devices, device-free floor, background checks |
| Handles hurricane and renewal peaks | Hard to add hours | Limited insurance knowledge | Yes, add hours or a second VA |
| Visibility into the work | In the office | Varies | Live dashboard logging every task |
Why South Carolina Insurance Agencies Are Turning to Virtual Assistants
Hurricanes and Severe Storms Drive the P&C Workload
According to NOAA’s billion-dollar disaster data for South Carolina, the state was affected by 101 confirmed billion-dollar weather and climate events between 1980 and 2024, including 44 severe storms and 25 tropical cyclones. The pace has picked up sharply, from a long-run average of 2.2 events a year to 6.2 a year in 2020–2024.
Hurricane Helene in 2024 showed that the risk isn’t only coastal. Flooding and wind damage hit Greenville, Spartanburg and the rest of the Upstate, where very few homeowners carry flood coverage. Every event brings a wave of first notice of loss calls, claim follow-ups, policy changes and renewal questions. Virtual assistants for South Carolina insurance agencies keep that service on track while licensed staff focus on clients.
Coastal Property Means Extra Placements
Along the coast, the South Carolina Wind and Hail Underwriting Association (the “wind pool”) provides wind and hail coverage for eligible property in coastal areas when the voluntary market won’t. A wind pool policy has to be placed through a licensed agent, and it usually sits alongside a separate homeowners or commercial policy and a flood policy. That means more applications, more renewals and more documents to track for agencies in Charleston, Myrtle Beach, Beaufort and Hilton Head.
The state’s SC Safe Home grant program, which helps eligible coastal homeowners strengthen roofs and openings, adds another layer of paperwork when clients ask for help documenting upgrades.
Residual Markets Add Paperwork
Beyond the wind pool, South Carolina’s auto residual market runs through the Associated Auto Insurers Plan, and workers’ compensation risks that can’t find coverage go to the assigned risk plan administered by NCCI. Each has its own applications, documentation and renewal rules. That is detailed, repeatable work, which makes it a good fit for a trained VA.
What Virtual Assistants Do Inside South Carolina Insurance Agencies
The day-to-day work of virtual assistants for insurance agencies in South Carolina usually covers:
- Renewal pipeline management, remarketing preparation and renewal reminders
- Wind pool, flood and homeowners applications, renewals and document requests
- Certificates of insurance for contractors working across Columbia, Charleston and the Upstate
- AMS and CRM data entry, carrier download matching and activity notes
- Endorsement and policy change processing
- First notice of loss intake and claim status follow-up after storms
- Workers’ compensation audit paperwork and employee benefits enrollment
- Commission statements, premium billing reconciliation and inbox management
What South Carolina Law Lets Virtual Assistants Do for Insurance Agencies
The Clerical Exemption in § 38-43-20
South Carolina requires a license to sell, solicit or negotiate insurance. S.C. Code § 38-43-20 also lists people who don’t need one. They include an employee of an insurer or producer who receives no commission on policies written or sold in South Carolina, if their activities are executive, administrative, managerial or clerical and only indirectly related to selling insurance. The section also covers an employee who performs only clerical duties and is paid by the hour or on salary, not on commission.
In plain English: virtual assistants working for South Carolina insurance agencies can handle a great deal of processing and administration, as long as they aren’t selling, recommending coverage or being paid on policies.
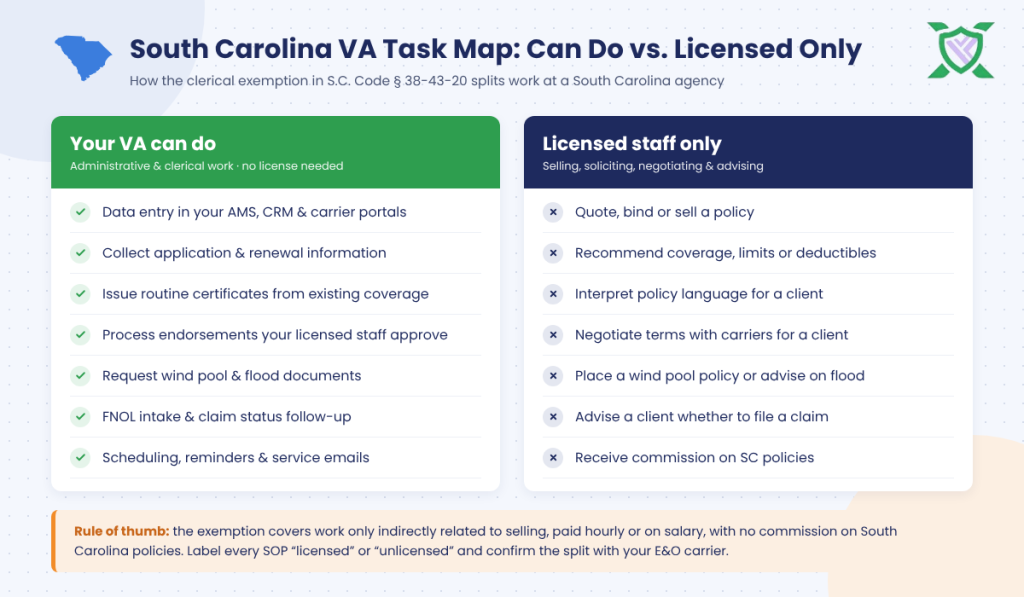
Tasks Virtual Assistants for South Carolina Insurance Agencies Can and Can’t Do
| A VA can do (no license needed) | Licensed staff must do |
|---|---|
| Data entry in your AMS, CRM and carrier portals | Quote, bind or sell a policy |
| Collect information for applications and renewals | Recommend coverage, limits or deductibles |
| Issue routine certificates from existing coverage | Interpret policy language for a client |
| Process endorsements your licensed staff approve | Negotiate terms with carriers on the client’s behalf |
| Request wind pool and flood documents | Place a wind pool policy or advise on flood coverage |
| FNOL intake and claim status follow-up | Advise a client on whether to file a claim |
| Scheduling, reminders and service emails | Receive commission on South Carolina policies |
Your E&O carrier may have its own view on where the line sits, so share your VA task list with them and label every SOP “licensed” or “unlicensed”.
How the South Carolina Department of Insurance Fits In
The South Carolina Department of Insurance licenses producers and agencies. Producer licenses renew every two years, by the end of the licensee’s birth month, and producers need 24 hours of continuing education per two-year cycle.
The Department doesn’t publish guidance aimed specifically at virtual assistants. Compliance for virtual assistants at South Carolina insurance agencies therefore comes down to your own documentation: written task boundaries, a provider agreement confirming VAs won’t perform licensed activities, and no commission-based pay for unlicensed staff. A VA can also help your producers track license renewal dates and CE hours.
Data Security for Virtual Assistants at South Carolina Insurance Agencies
South Carolina was an early adopter of an insurance-specific data security law. The South Carolina Insurance Data Security Act, passed in 2018 and in force since January 1, 2019, applies to licensees of the Department, including producers and agencies. It matters directly when you bring in a VA:
- A written information security program. Licensees must keep a program based on a risk assessment, covering access controls, encryption, multi-factor authentication, staff training and an incident response plan.
- Oversight of service providers. Licensees must use due diligence when selecting a third-party service provider and require it to protect the systems and nonpublic information it can access. A VA provider is exactly that kind of service provider.
- 72-hour notice. A cybersecurity event generally has to be reported to the Director of Insurance within 72 hours of determining that it happened.
- Small agency exemption. Licensees with fewer than ten employees, counting independent contractors, are exempt from the information security program requirement, but not from the notification rules.
Before you give any VA access, check how the provider handles logins, devices, training and breach notification. We cover the full checklist in Is Your Client Data Safe Offshore? NPI, SOC 2 & What to Demand from a VA Provider.
What to Look for in Virtual Assistants for Insurance Agencies in South Carolina
Not every VA is ready for insurance work. Before you sign with anyone, check for these seven things.
1. Insurance Training, Not Just General Admin
Your VA should already understand renewals, endorsements, certificates, loss runs and carrier downloads. If you have to explain what a dec page is, you’re paying to train them.
2. Experience in Your AMS
Ask which agency management systems the VA has actually worked in. Real experience in AMS 360, Applied Epic, EzLynx or HawkSoft saves weeks of ramp-up.
3. A Clear Licensed vs. Unlicensed Boundary
The provider should confirm in writing that VAs won’t quote, bind, sell or advise on coverage, and should never pay VAs on commission. That keeps you inside the clerical exemption in § 38-43-20.
4. Coastal and Commercial Experience, Not Just Auto and Home
South Carolina books carry wind pool policies, flood applications, contractor certificates and workers’ compensation paperwork. Make sure the VA can handle commercial lines work as well as personal lines service.
5. Proven Data Security Controls
Look for named logins, multi-factor authentication, encrypted devices, a password manager, background checks and physical security at the provider’s office. Ask to see the provider’s security and compliance controls so you can document your due diligence under the Data Security Act.
6. Visibility Into the Work
You should be able to see what your VA did, when and for which client, without chasing them for updates.
7. A Real Trial Period
A trial on your own workload is the only reliable test. Be wary of long contracts before you’ve seen any work.
How XAssure’s Virtual Assistants Support South Carolina Insurance Agencies
XAssure provides insurance-trained VAs for personal lines, commercial lines and employee benefits work, built around the checklist above. See how it works from discovery call to full service:
- Insurance-trained from day one: renewals, certificates, endorsements, loss runs, FNOL intake, wind pool and flood paperwork, and enrollment processing
- Works in your systems: AMS 360, Applied Epic, EzLynx, HawkSoft, NowCerts and QQ Catalyst, plus major carrier portals
- Clear task boundaries: every SOP is labeled licensed or unlicensed, VAs are never paid on commission, and work is overseen by US licensed agent management
- Security first: MFA, least-privilege access, BitLocker-encrypted computers, mobile device management, background checks, a device-free office floor and 24/7 physical security
- Live dashboard: every task is logged with real-time timers, so you see the work as it happens
- Dedicated account manager: one point of contact for quality, cover and extra hours in hurricane or renewal season
- Low risk: a 2-week free trial before any commitment
Best for: South Carolina agencies that need one team to cover hurricane-season P&C service, coastal wind and flood paperwork and commercial certificates without adding a local salary.
What Do Virtual Assistants for Insurance Agencies in South Carolina Cost?
Bureau of Labor Statistics data put the median wage for insurance claims and policy processing clerks at $44,650 in South Carolina in 2025, against $49,230 nationally (see O*NET’s wage data for South Carolina). Experienced CSRs usually earn more than that, and once you add payroll taxes, health benefits, PTO, equipment and recruiting time, a full-time in-house hire costs far more than the salary line. Here is how that compares with virtual assistants for insurance agencies in South Carolina.
| Cost item | In-house CSR (South Carolina) | XAssure dedicated VA | Budget generalist VA |
|---|---|---|---|
| Base pay | $40,000–$50,000 | Included | Included |
| Payroll taxes and benefits | $10,000–$16,000 | None | None |
| Equipment, software, office | $3,000–$6,000 | None | Varies |
| Recruiting and turnover risk | High | Replacement included | Your problem |
| Insurance training | Your time | Already trained | Your time |
| Estimated annual cost | $53,000–$72,000 | $12,600 (part-time) to $24,000 (full-time) | Roughly $8,000–$17,000 |
In-house figures are estimates; your local wages will vary. For a fuller breakdown, see the true cost of hiring an insurance CSR.
How to Onboard Virtual Assistants in South Carolina Insurance Agencies
Build Your SOPs Before Day One
Write a short step-by-step SOP and record a screen walkthrough for each task you plan to hand over. Label each one “licensed” or “unlicensed” so the boundary under § 38-43-20 is clear from the start. Our guide to writing SOPs your VA can actually follow includes templates you can copy.
Set Up Secure AMS and Carrier Access
Create a named VA user in your AMS and each carrier portal with only the permissions they need. Use multi-factor authentication and a business password manager, and never share a producer’s login. Record the provider in your written information security program, and keep your due diligence on file.
Then plan the first 30 days in three stages:
- Week 1: System access, shadowing and low-risk tasks such as data entry and certificates
- Weeks 2–3: Supervised work on renewals, endorsements and wind pool or flood paperwork, with daily check-ins
- Week 4: Independent work with a weekly quality review
Our guide on how to onboard an insurance virtual assistant walks through every step.
Summing Up
South Carolina insurance agencies face hurricane-driven service spikes, coastal wind pool and flood placements, residual market applications and a tight hiring market. The right virtual assistant partner for a South Carolina agency brings real insurance training, respects the licensed and unlicensed boundary in § 38-43-20, supports your obligations under the Insurance Data Security Act, and works inside the AMS you already use.
Use the checklist to judge any provider, and onboard with documented SOPs and secure access. When you’re ready to test it with your own workload, XAssure gives you an insurance-trained VA, a dedicated account manager and a live dashboard, free for the first two weeks.
Frequently Asked Questions
Not for administrative work. S.C. Code § 38-43-20 exempts agency employees whose work is executive, administrative, managerial or clerical and only indirectly related to selling insurance, and who receive no commission on South Carolina policies. A VA cannot quote, bind, sell or advise on coverage.
Insurance-trained VAs typically cost far less than an in-house hire. XAssure plans start at $1,050 per month for 20 hours a week and $2,000 per month for 40 hours a week, compared with an estimated $53,000 to $72,000 a year for a fully loaded in-house CSR in South Carolina.
Yes, it applies to licensees including producers and agencies. Agencies with fewer than ten employees, counting independent contractors, are exempt from the information security program requirement, but every licensee must still follow the cybersecurity event notification rules.
Yes. A VA can collect application details, request documents, track renewals and follow up with clients. Placing a wind pool policy and advising a client on wind or flood coverage stay with licensed staff.
XAssure VAs work in AMS 360, Applied Epic, EzLynx, HawkSoft, NowCerts and QQ Catalyst, along with carrier portals and ACORD forms.
The South Carolina Department of Insurance licenses producers and agencies. Producer licenses renew every two years by the end of the licensee’s birth month, and producers need 24 hours of continuing education per cycle.
Also Reads
- Virtual Assistants for Insurance Agencies by State: The 2026 Guide
- Best Virtual Assistants for Insurance Agencies in North Carolina [2026 Guide]
- Best Virtual Assistants for Insurance Agencies in Georgia [2026 Guide]
- Best Virtual Assistants for Insurance Agencies in Maryland [2026 Guide]
- Writing SOPs Your VA Can Actually Follow (With Templates)
This article is for general information and is not legal advice.